functionquantile
Quantile of truncated normal distribution
Extends from Modelica.Math.Distributions.Interfaces.partialTruncatedQuantile (Common interface of truncated quantile functions (= inverse cumulative distribution functions)).
Information
Syntax
Normal.quantile(u, y_min=0, y_max=1, mu=0, sigma=1);
Description
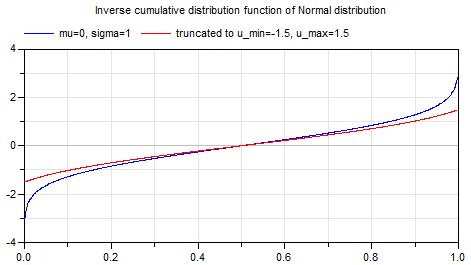
This function computes the inverse cumulative distribution function (= quantile) according to a truncated normal distribution with minimum value u_min, maximum value u_max, mean value of original distribution mu and standard deviation of original distribution sigma (variance = sigma2). Input argument u must be in the range:
0 < u < 1
Output argument y is in the range:
y_min ≤ y ≤ y_max
Plot of the function:
For more details
of the normal distribution, see
Wikipedia,
of truncated distributions, see
Wikipedia.
Example
quantile(0.001)           // = 0.001087357613043849;
quantile(0.5,0,1,0.5,0.9) // = 0.5
See also
Inputs
| Type | Name | Default | Description |
|---|---|---|---|
| Real | u (from partialQuantile) | Random number in the range 0 <= u <= 1 | |
| Real | y_min (from partialTruncatedQuantile) | 0 | Lower limit of y |
| Real | y_max (from partialTruncatedQuantile) | 1 | Upper limit of y |
| Real | mu | (y_max + y_min)/2 | Expectation (mean) value of the normal distribution |
| Real | sigma | (y_max - y_min)/6 | Standard deviation of the normal distribution |
Outputs
| Type | Name | Default | Description |
|---|---|---|---|
| Real | y (from partialQuantile) | Random number u transformed according to the given distribution |
Revisions
| Date | Description | ||
|---|---|---|---|
| June 22, 2015 |
|
